
GROW with SAP: Evaluating Implementation Costs Against Expected ROI
Quick Answer
GROW with SAP implementation costs include cloud ERP subscriptions, consulting, configuration, data migration, integrations, employee training and ongoing support. Businesses should evaluate these expenses against measurable financial and operational benefits using total cost of ownership (TCO), return on investment (ROI) and payback period. A successful investment depends on realistic financial projections, implementation readiness and effective user adoption.
The Financial Commitment Behind GROW with SAP
For growing businesses, ERP investment is not simply a technology purchase. It is a financial decision that can influence operational efficiency, profitability and long-term scalability.
GROW with SAP, now known as SAP GROW, is a cloud ERP offering built around SAP S/4HANA Cloud Public Edition. It supports businesses looking to adopt standardised processes and a scalable, SAP-managed ERP environment.
However, selecting the right ERP solution is only part of the decision. Understanding the complete financial commitment is equally important.
A subscription proposal may provide visibility into software expenditure, but it does not necessarily represent the entire cost of preparing, implementing and operating the solution.
Before approving an ERP investment, executives need to understand three distinct cost categories:
- Initial investment: Expenses associated with implementation and deployment.
- Recurring expenditure: Ongoing subscriptions, support and application commitments.
- Financial risk exposure: Potential additional costs resulting from delays, rework or changes in scope.
Evaluating these categories together provides a more accurate foundation for investment planning.
Key Factors Influencing GROW with SAP Implementation Costs
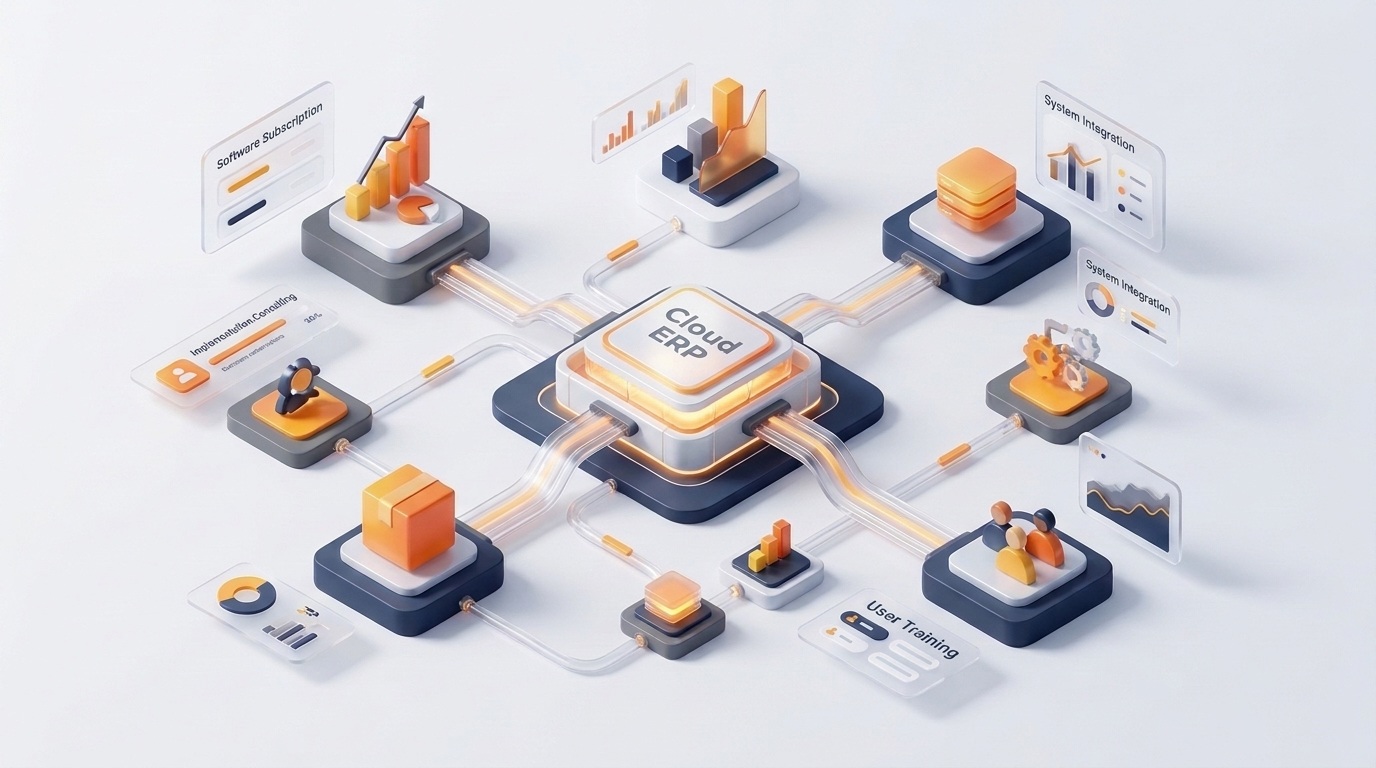
Key expenditure categories across subscription licensing, professional consulting, migration pipelines, integrations, and organisational training.
The actual cost of implementing GROW with SAP varies according to business complexity, organisational requirements, subscription arrangements and project scope.
Understanding the individual cost components helps decision-makers evaluate implementation proposals more effectively.
Cloud ERP Subscription and Licensing
Subscription costs depend on the contracted package, required capabilities, applicable usage metrics and commercial terms.
Businesses should review:
- Included software and services.
- Subscription duration and renewal conditions.
- Additional application or extension requirements.
- Potential changes in subscription commitments as the organisation grows.
Unlike traditional on-premise ERP deployments, SAP S/4HANA Cloud Public Edition is hosted and managed by SAP. Businesses should therefore avoid automatically including infrastructure expenses that do not apply to their chosen deployment model.
Customer-side networking, integrations, devices and other IT responsibilities may still require separate investment.
Implementation and Consulting Services
Implementation expenditure includes the professional services required to prepare, configure, test and deploy the ERP solution.
The scope may cover finance, procurement, sales, inventory, manufacturing and other applicable business processes.
Organisations operating across multiple locations or legal entities may require additional coordination, localisation and process validation.
A detailed statement of work should identify project deliverables, responsibilities, assumptions, exclusions and acceptance criteria.
Data Migration and System Integration
Data quality has a direct influence on implementation effort.
Duplicate customer records, inconsistent material information, unreconciled financial balances and incomplete historical data can increase migration complexity.
Businesses must also assess integration requirements involving existing applications such as CRM, banking, payroll, warehouse management and tax platforms.
Each integration should have a defined business purpose, technical scope and support responsibility.
Employee Training and Organisational Readiness
ERP adoption requires employees to understand revised workflows and responsibilities.
Training programmes, process workshops, user acceptance testing and change management require dedicated resources. Internal employees may also need to allocate significant time to implementation activities.
These commitments should be included in the financial assessment rather than treated as cost-free participation.
Implementation Cost Breakdown
| Cost component | Typical expenditure | Cost category |
|---|---|---|
| Cloud ERP subscription | Contracted software and services | Recurring |
| Implementation consulting | Process design and deployment | One-time |
| Data migration | Cleansing, mapping and reconciliation | One-time |
| System integration | Configuration, development and testing | One-time and recurring |
| Employee training | User onboarding and refresher training | One-time and recurring |
| Additional applications | Extensions and complementary solutions | One-time and recurring |
| Post-go-live support | Applicable support and optimisation | Recurring |
A comprehensive budget should classify each expense by timing, ownership and contractual responsibility.
Hidden ERP Expenses That Can Increase Your Investment
Even a carefully prepared implementation estimate can change when previously unidentified requirements emerge.
The financial challenge is not simply the existence of additional expenses. It is approving an ERP project without understanding where these expenses could originate.
Scope Expansion During Implementation
New reporting requirements, approval workflows and business processes may emerge after implementation workshops begin.
Some changes are essential. Others result from shifting preferences or incomplete initial requirements.
Without formal change control, additional requests can increase consulting expenditure and extend the implementation schedule.
Every significant scope change should include a business justification, cost assessment and approval.
Unnecessary Extensions and Customisation
SAP S/4HANA Cloud Public Edition supports a fit-to-standard implementation approach. Businesses evaluate standard processes before deciding whether additional configuration or supported extensions are necessary.
Attempting to reproduce every legacy workflow can increase project complexity without delivering equivalent business value.
Where extensions are justified, organisations should assess development, testing, licensing and ongoing maintenance requirements.
A clean-core approach helps businesses preserve standard ERP functionality while addressing genuine requirements through supported extensibility options.
Rework and Operational Stabilisation
Migration defects, incomplete testing and unresolved integration dependencies can create additional implementation effort.
After deployment, businesses may also require stabilisation support to resolve operational issues and help employees adapt to revised processes.
These requirements should be distinguished from the original planned activities to avoid double-counting expenditure.
Financial safeguard: Maintain a cost register that identifies potential additional expenses, their likelihood, estimated impact and approval responsibility. Allocate contingency funding based on identified risks rather than an arbitrary percentage.
Implementation Risks That Can Delay ERP Returns
An ERP project can remain within its original software budget and still fail to deliver expected business returns.
Implementation delays, inaccurate information and low employee adoption can postpone the operational improvements used to justify the investment.
The result is a longer period before the organisation begins recovering its costs.
| Implementation risk | Potential business impact | Preventive control |
|---|---|---|
| Schedule delays | Additional project costs and delayed benefits | Milestone-based governance |
| Poor data quality | Incorrect reporting and transaction errors | Migration validation and reconciliation |
| Integration failures | Disrupted information flow | End-to-end interface testing |
| Low user adoption | Continued manual workarounds | Role-based training and change management |
| Process misalignment | Inefficient workflows and additional configuration | Fit-to-standard workshops |
| Uncontrolled scope changes | Budget overruns | Formal change approval |
Managing Implementation Through Measurable Milestones
SAP Activate provides a structured methodology for planning and delivering SAP implementations.
Rather than assessing progress solely through completed technical activities, project leaders should establish measurable business acceptance criteria.
Before approving deployment, management should confirm that:
- Critical business processes have been tested.
- Migrated financial and operational records have been reconciled.
- Required integrations operate correctly.
- Employees are prepared to perform their assigned roles.
- Support and escalation responsibilities are established.
These controls help reduce the risk of going live with unresolved business-critical issues.
Business Value Drivers Behind Cloud ERP ROI
The return on a GROW with SAP investment depends on the operational improvements a business can achieve and sustain.
An ERP system alone does not guarantee higher profitability. The value comes from how effectively the organisation uses its capabilities to improve processes, reduce inefficiencies and strengthen financial control.
Improved Financial Reporting and Visibility
Disconnected financial systems can delay reporting and increase reconciliation effort.
An integrated ERP environment can provide a more consistent foundation for financial reporting, transaction monitoring and management analysis.
Finance teams can evaluate the resulting improvements through reporting cycle time, reconciliation hours and month-end closing performance.
Reduced Manual Processing and Administrative Effort
Repeated data entry, spreadsheet-based approvals and disconnected applications consume employee time.
Standardised workflows can reduce avoidable manual activities and improve transaction consistency.
However, employee time saved should not automatically be classified as cash savings. Financial benefits depend on whether the business reduces actual expenditure, avoids additional hiring or converts available capacity into productive work.
Stronger Inventory and Procurement Control
Inconsistent inventory records and purchasing processes can contribute to stock discrepancies, excess inventory and unnecessary procurement expenditure.
Improved transaction visibility and process coordination may help businesses strengthen inventory accuracy and purchasing decisions.
The financial impact should be assessed through measurable changes in inventory correction costs, purchasing exceptions and working capital requirements.
Greater Operational Scalability
Growing organisations often encounter increasing complexity as they add employees, locations, products and business transactions.
Standardised processes can help businesses manage expansion without increasing administrative effort at the same rate as business growth.
This potential value should be evaluated against realistic growth forecasts and the additional resources that would otherwise be required.
Measuring ERP Performance Through Business KPIs
Before implementation begins, executives should establish measurable baselines for the operational problems they expect the ERP investment to address.
| Business objective | Recommended KPI | Business owner |
|---|---|---|
| Faster financial reporting | Month-end closing duration | CFO |
| Reduced manual work | Administrative processing hours | Process owners |
| Improved stock control | Inventory record accuracy | Supply chain head |
| Better procurement efficiency | Purchase order processing time | Procurement head |
| Stronger process consistency | Transaction exception rate | Operations head |
| Faster management decisions | Reporting availability and preparation time | Finance and management |
Each KPI should have a defined baseline, target, measurement frequency and accountable owner.
For example, a finance department that currently requires ten working days to complete its month-end close can establish a target of seven days after implementation.
This is a measurable operational objective. Its financial value must then be assessed separately through reduced overtime, external expenses or other demonstrated benefits.
A reliable ROI model starts with measurable business problems rather than assumed percentage improvements.
Evaluating GROW with SAP ROI Through Total Cost of Ownership

Evaluating multi-year total cost of ownership against cumulative financial gains and operational performance returns.
Total cost of ownership represents the complete cost of acquiring, implementing, operating and supporting an ERP solution over a specified evaluation period.
It provides a broader financial perspective than the initial implementation proposal.
Building the Total Cost of Ownership Model
A practical TCO assessment includes:
The evaluation period should reflect the organisation’s financial planning horizon and contractual commitments.
Finance teams should account for when each expense occurs, rather than comparing an annual benefit directly with a multi-year investment.
Calculating ERP Return on Investment
The standard ROI calculation is:
The corresponding net financial benefit is:
Businesses should also evaluate the payback period, which represents the time required for cumulative net benefits to recover the initial investment.
For larger investments, CFOs may use discounted cash flow and net present value (NPV) to account for the timing of costs and returns.
Illustrative Three-Year ERP Investment and ROI
Consider a hypothetical growing business evaluating its cloud ERP investment over three years.
| Financial component | Illustrative amount |
|---|---|
| Implementation and consulting | ₹40 lakh |
| Internal project resources and training | ₹10 lakh |
| Annual recurring ERP expenditure | ₹20 lakh |
| Total recurring expenditure over three years | ₹60 lakh |
| Three-year total cost of ownership | ₹110 lakh |
| Measurable financial benefits over three years | ₹150 lakh |
| Net financial benefit | ₹40 lakh |
| Three-year ROI | 36.4% |
In this scenario, the total investment is ₹1.10 crore, while the measurable financial benefits amount to ₹1.50 crore.
The investment generates an illustrative undiscounted ROI of approximately 36.4% over three years.
These figures are hypothetical and are not SAP pricing, a customer case study or a guaranteed financial outcome.
The purpose of this example is to demonstrate how implementation expenditure, recurring costs and measurable benefits influence ERP investment returns.
The Financial Impact of Delayed Benefits
Assume the same organisation experiences implementation delays or lower-than-expected adoption.
If its three-year financial benefits decline from ₹150 lakh to ₹120 lakh while costs remain unchanged, the ROI falls to approximately 9.1%.
| Scenario | Three-year benefits | Three-year TCO | ROI |
|---|---|---|---|
| Conservative | ₹120 lakh | ₹110 lakh | 9.1% |
| Expected | ₹150 lakh | ₹110 lakh | 36.4% |
| Favourable | ₹180 lakh | ₹110 lakh | 63.6% |
This sensitivity analysis demonstrates why executives should assess multiple financial scenarios instead of relying on a single optimistic projection.
In an actual implementation, delays could also increase project costs, further reducing the expected return.
Executive Investment Assessment for SAP GROW
A financially attractive ROI projection is not enough to justify an ERP investment if the proposed solution does not align with business requirements.
Before approving GROW with SAP, executives should assess five critical dimensions.
| Evaluation area | Key decision consideration |
|---|---|
| Business process fit | Alignment between standard SAP processes and operational requirements |
| Technical suitability | Data readiness, integration dependencies and supported extensibility |
| Organisational readiness | Availability of project resources and business process owners |
| Financial feasibility | Affordability, total ownership cost and realistic benefit projections |
| Long-term scalability | Alignment with future business growth and operating requirements |
Establishing Executive Accountability
The investment decision should involve more than the IT department.
The CEO must establish the business objectives, while the CFO validates financial assumptions and expected returns. The CIO or CTO assesses technical suitability, and operational leaders confirm process requirements and employee readiness.
A coordinated assessment reduces the likelihood of approving an ERP project based solely on software functionality or commercial attractiveness.
Where significant business or technical gaps remain unresolved, organisations should assess alternative ERP approaches before committing to implementation.
Conclusion
The real value of GROW with SAP lies in its ability to support measurable business improvements that justify the complete ERP investment.
A lower implementation estimate does not necessarily deliver a higher ROI. Similarly, a higher initial investment may be commercially justified when it supports stronger financial control, operational efficiency and sustainable business growth.
Executives should prioritise realistic cost planning, validated business requirements, disciplined implementation governance and measurable performance objectives.
By evaluating total cost of ownership alongside expected financial benefits, businesses can make a more informed cloud ERP investment decision and establish a stronger foundation for long-term value creation.
Frequently Asked Questions
Maximise Your ERP Investment with GROW with SAP
Make your next ERP investment an informed business decision.
Explore how GROW with SAP can support your operational requirements, financial objectives and long-term growth plans. Emerging Alliance can help you assess implementation scope, identify cost considerations and evaluate potential business returns.
Book Your GROW with SAP Demo with Emerging Alliance.